Two Screens, One Choice: The Lie Of ‘NAZA’ And The Truth Of ‘Fauda’
While a libelous Israeli film was rewarded in Venice with a jury prize and a standing ovation, the...
 Queens Jewish Link
Connecting the Queens Jewish Community
While a libelous Israeli film was rewarded in Venice with a jury prize and a standing ovation, the...


It’s no secret that my pickle obsession is real. I strongly believe that (most) things are better homemade, and here’s a solid sour pickle recipe to prove it
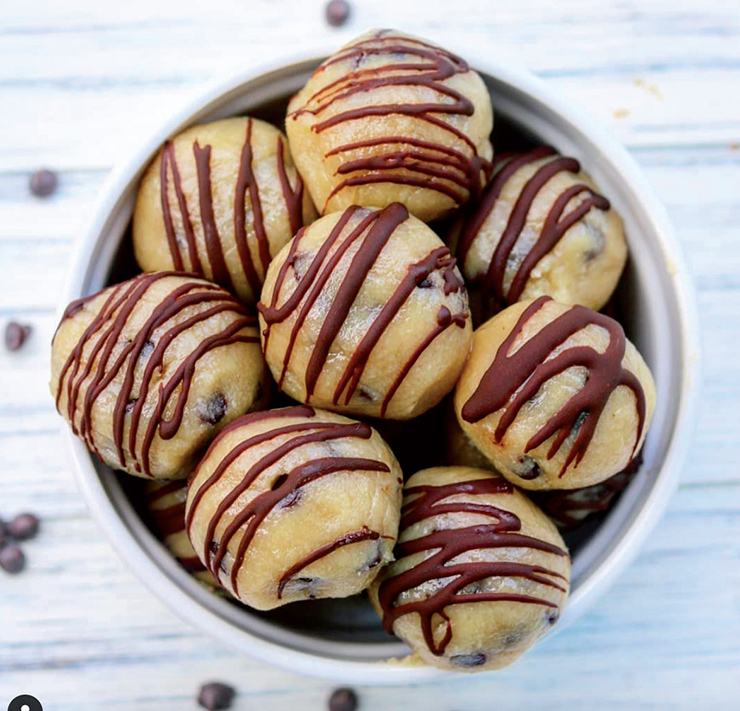
Attention all cookie dough lovers! Get your fix with these delicious, no-bake cookie dough bites! They're fun to eat as little bites or even with a spoon! They're also completely gluten-free and kosher for Passover!
Failing to establish or maintain a proper estate plan is one of the most expensive mistakes a family can make. It frequently results in frozen bank accounts, prolonged court battles, and asset distribution that completely goes against your actual wishes. Avoiding these five common blind spots protects your legacy and saves your family thousands.
The cost of long-term care can destroy a lifetime of savings in a matter of months. Many families mistakenly believe they have only two options: pay out of pocket until they are completely broke or rely on a nursing home right away. Fortunately, you can protect your hard-earned assets and secure high-quality care, but only if you understand the strict legal frameworks governing long-term care.
The greatest threat to an estate plan isn’t taxes or market drops, rather, it is family conflict. When a parent passes away, unsettled tensions and financial stress can turn a lifetime of hard work into a bitter, multi-year courtroom battle. Protecting your assets means nothing if your children stop speaking to one another. You can proactively insulate your family from post-death disputes by focusing on four strategic areas.
There are two kinds of dads. The first shows up. He never misses a game, helps with school projects and homework, loves his family fiercely, and works very hard to provide for them. The second kind does all of that, and he also has a plan. He understands that protecting his children means securing their future, even if he isn’t there to do it himself.